Teaching Kids Financial Literacy: The Complete Age-by-Age Guide for Smart Money Habits
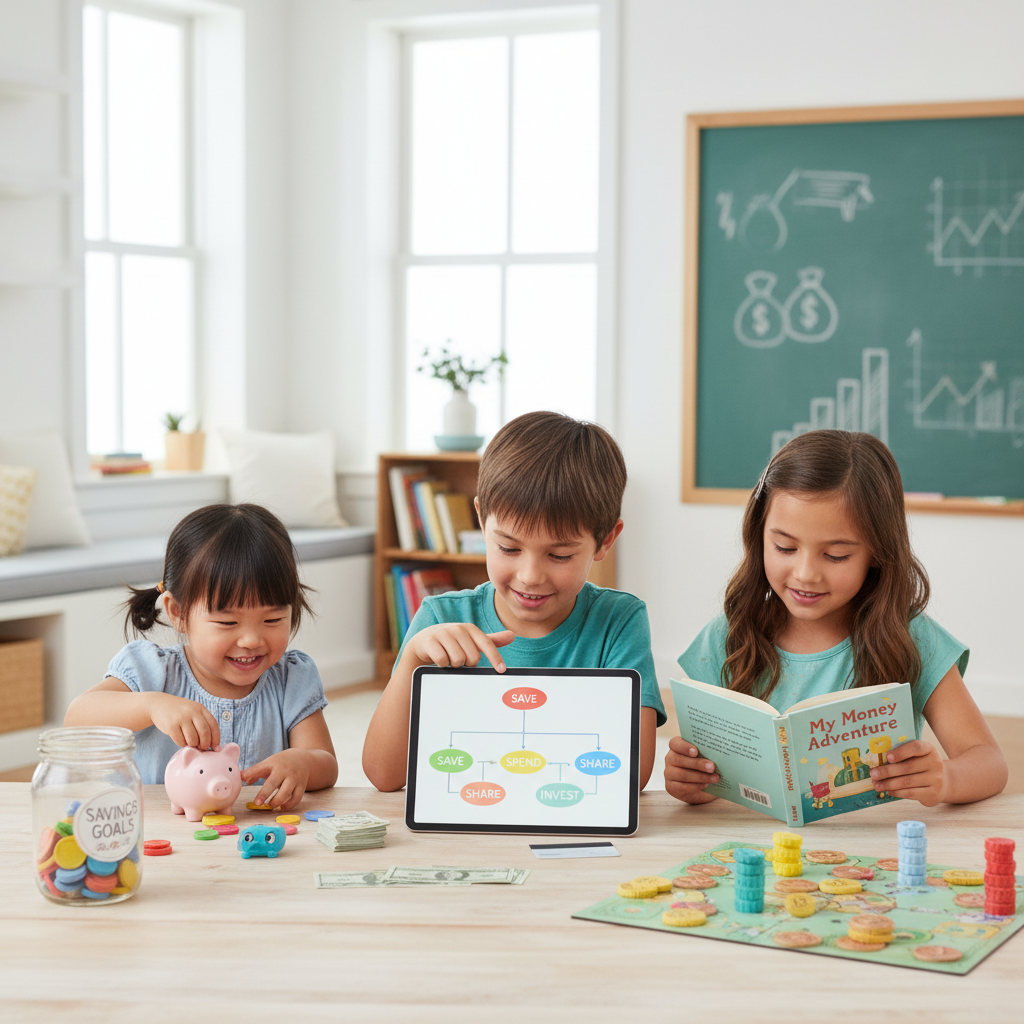
Teaching kids financial literacy is one of the most valuable and overlooked areas of childhood education. While schools spend hundreds of hours on reading, math, and science, financial education receives almost no attention in most curricula. According to the Council for Economic Education, only 26 of the 50 U.S. states require any form of personal finance education in high school, and virtually none address it at the elementary level. This means the responsibility falls squarely on parents, and the evidence shows that starting early produces dramatically better outcomes.
Why Financial Literacy Matters More Than Ever
A 2025 study by the Financial Industry Regulatory Authority (FINRA) found that adults who received financial education as children were 75% more likely to have emergency savings, 50% less likely to carry credit card debt, and 30% more likely to be investing for retirement. Dr. Brad Klontz, a financial psychologist at Creighton University, notes: "Money habits are largely formed by age seven. The attitudes, beliefs, and behaviors children develop around money in their early years persist into adulthood with remarkable consistency."
Research from the University of Cambridge commissioned by the UK's Money Advice Service confirmed this finding, concluding that children's core money habits are established by age seven and are extremely difficult to change afterward. This underscores the urgency of starting financial education early, long before children are old enough for a formal economics class.
Ages 3-5: Building the Foundation
Preschoolers cannot understand compound interest, but they can grasp surprisingly sophisticated financial concepts when presented in age-appropriate ways:
- Coin identification and counting: Start with physical coins. Let children sort, count, and compare coins. This builds number sense while introducing the concept that money has different values. According to Dr. Lewis Mandell, a financial literacy researcher, tactile interaction with money is more effective for young children than digital or abstract representations.
- Needs vs. wants: Begin conversations about the difference between things we need (food, shelter, clothing) and things we want (toys, candy, entertainment). Use grocery shopping as a real-world classroom.
- Delayed gratification: The famous "marshmallow experiment" at Stanford demonstrated that children who could delay gratification achieved better life outcomes. Practice this by saying "we can buy that next week" and following through, teaching that waiting is a skill that pays off.
- Play store: Set up a pretend shop at home where children "buy" and "sell" items using play money. This introduces the concept of exchange and value in a fun, low-pressure context.
Ages 6-9: Introducing Earning and Saving
Elementary school children are ready for more concrete financial experiences:
- Allowance system: Financial educators debate whether allowance should be tied to chores. The American Institute of CPAs recommends a hybrid approach: provide a small base allowance for being part of the family, with opportunities to earn extra money through additional tasks. This teaches both financial security and the connection between work and income.
- The three-jar system: Give your child three clear jars labeled "Save," "Spend," and "Give." When they receive money, they divide it among the three jars. This simple system teaches budgeting, saving, and generosity simultaneously. A 2024 study by Junior Achievement found that children who used a physical savings system were 60% more likely to maintain savings habits as teenagers.
- Comparison shopping: Involve children in purchasing decisions. "This brand costs $3 and this one costs $5. They are very similar. Which should we choose?" This teaches value assessment and critical consumer thinking.
- Saving for goals: Help your child identify something they want and create a savings plan. Chart their progress visually. The experience of saving over weeks or months and finally making a purchase with their own money is profoundly formative.
Ages 10-13: Understanding the Financial System
Preteens are ready to engage with real financial institutions and more complex concepts:
- Bank accounts: Open a savings account in your child's name. Many banks offer youth accounts with no minimum balance. The act of depositing money, watching it grow, and understanding interest (even at today's modest rates) makes abstract concepts concrete. According to a 2025 report by the Consumer Financial Protection Bureau, children who have a savings account are seven times more likely to attend college.
- Budgeting: Give your child responsibility for a specific expense category, such as their entertainment budget or school supplies budget. Provide a fixed amount and let them manage it. When the money runs out, resist the urge to supplement. Running out of budget money is one of the most effective financial lessons a child can experience.
- Entrepreneurship basics: Encourage lemonade stands, pet-sitting, lawn mowing, or selling crafts. These micro-businesses teach profit, expense management, customer service, and the value of hard work. The Kauffman Foundation reports that children who start small businesses develop stronger financial decision-making skills than peers who receive only classroom financial education.
- Understanding advertising: Teach children to recognize marketing tactics. "Why do you think they put candy at eye level near the checkout?" This builds critical thinking about spending impulses and consumer manipulation.
Ages 14-18: Preparing for Financial Independence
Teenagers need to develop the skills they will use as independent adults:
- Part-time work: The Bureau of Labor Statistics data shows that teens who work part-time during high school develop stronger financial habits than those who do not. A first paycheck, complete with tax withholdings, is an eye-opening financial education.
- Introduction to investing: Open a custodial investment account and let your teen choose index funds or individual stocks with guidance. Apps like Greenlight and Fidelity Youth offer teen-friendly investment platforms. According to Fidelity's 2025 Youth Investment Report, teens who start investing before age 18 accumulate three times more wealth by age 30 than those who start at 22.
- Credit education: Explain how credit works, what credit scores mean, and the true cost of debt. Use real examples: "If you put $1,000 on a credit card at 20% interest and only make minimum payments, you will pay $1,400 total." Consider adding your teen as an authorized user on a credit card to begin building their credit history responsibly.
- College financial planning: Involve your teen in understanding college costs, scholarships, financial aid, and student loan implications. According to the Institute for College Access and Success, the average student loan debt for 2025 graduates exceeded $33,000. Teens who understand these numbers make more informed decisions about where and how to pursue higher education.
Common Mistakes Parents Make
Even well-intentioned parents can undermine financial education. Avoid these common pitfalls:
- Never talking about money: Treating money as a taboo topic leaves children to develop financial attitudes from advertising and peers, which are rarely healthy sources. Age-appropriate transparency about family finances builds financial awareness.
- Bailing them out: When your child spends their entire allowance on Monday and wants more on Wednesday, the instinct to help is strong. But experiencing the natural consequences of financial decisions is one of the most powerful teachers.
- Only focusing on earning and saving: Financial literacy also includes spending wisely, giving generously, and understanding risk. A balanced approach produces well-rounded financial thinkers.
- Not modeling good habits: Children learn more from what they observe than what they are told. If parents consistently overspend, avoid budgeting, or express anxiety about money, children absorb those patterns. According to a 2024 study in the Journal of Family and Economic Issues, parental financial behavior is the single strongest predictor of children's future financial behavior.
Teaching your child about money is not about raising the next Warren Buffett. It is about giving them the knowledge, habits, and confidence to make sound financial decisions throughout their lives. Start today with one age-appropriate conversation or activity, and build from there. The financial skills you teach now will compound over a lifetime, delivering returns far greater than any investment.
Written by
You might also like
 81
Best Creative Craft Kits for Kids: Art Projects They'll Actually Finish
Discover the best creative craft kits for kids that they will actually finish. From sculpting and glass painti...
Our Favorite Ways to Bring Love, Peace, and Whimsy Into Your Child's World
From imaginative play sets to calming mindfulness tools, these are our favorite picks that bring love, peace,...
Our Favorite Bring Your Love, Peace, and Whimsy! Toys and Gifts for Kids
Discover 8 whimsical toys and gifts that bring love, peace, and creative wonder into your child's world while...